🏛️ Joint Venture Property Investment

Your Deposit.
Our Expertise.
Shared Returns.

You put in the deposit. We source, refurbish, let, and manage everything. You own the asset, earn the income, and pull your capital back out through refinance.

25%
Typical deposit required
8–12%
Target annual yield
50/50
Net rent split
3–5yr
Capital release timeline
Try the Calculator ↓ ⬇ Download Brochure
The Model

How the JV Works

A fully transparent joint venture — you bring the deposit, we bring everything else.

01

You Provide the Deposit

You invest your deposit — typically 25–30% of the purchase price. A bridging loan covers the remaining 70–75%, secured against the property. No large mortgage in your name yet.

💷 Your Capital In
02

We Source & Acquire

Our team locates off-market Victorian properties in South-East London primed for HMO conversion, typically acquired 10–20% below market value. We handle the entire purchase process.

🔍 Off-Market Sourcing
03

Full Refurbishment (~£200k)

Complete HMO conversion: planning, building regulations, fire compliance, HMO licensing, en-suite bathrooms, designer fit-out. Every certificate secured. This dramatically increases the Gross Development Value.

🏗️ Full Conversion
04

Let, Then Refinance

Once tenanted, we get a RICS valuation at the new GDV and refinance with a BTL lender at 75% LTV. This pays off the bridge in full — and any surplus is returned directly to you, reducing your net capital invested.

🏦 Bridge Repaid · Surplus to You
05

You Own It. We Run It.

The property is in your name. We manage everything — tenants, maintenance, compliance, statements. You receive 50% of net rent after mortgage payments every month. We take 50% as our management fee.

🔑 Asset in Your Name
06

Capital Release in 3–5 Years

After 3–5 years of property appreciation, we refinance again at the higher GDV — releasing a further lump sum to you. In the best cases, you end up owning a fully tenanted asset with zero net capital remaining in it.

📈 Pull Your Money Out
Interactive Tool

Investment Returns Calculator

Model your exact deal. Includes SDLT, purchase costs, refurbishment extras, and a 5-year comparison against alternative investments. All figures are illustrative projections.

① Acquisition
SE London Victorian terraces: £300k–£850k
Deposit = purchase − bridge
% of facility
Annual %
Months on bridge
② Refurbishment
Full HMO conversion inc. fit-out & compliance
Buffer on top of core refurb — almost always used
③ Rental Income
HMO licence: 5+
Bills-included rate
5% = 18 days vacant/room/yr · 109 days across 6 rooms
④ Valuation & Refinance
Applied to net income → GDV. Lower yield = higher valuation
Refinance LTV
Mortgage rate
⑤ Growth & Exit
SE London avg: 4–6%
Exit at this year
⑥ Deal Thresholds
Critical break-even points calculated from your inputs above.
Min yield to return all capital—
Min rent/room to cover mortgage—
Min GDV to repay bridge—
Break-even rent (all costs)—
① Capital Required
Purchase price£500,000
Bridge loan (70%)£350,000
Your deposit (balance)£150,000
SDLT + purchase fees ⓘ £62,500
SDLT£37,500
Legal / solicitor£2,500
Survey & valuation£1,200
Arrangement fee£5,250
Broker + searches£1,500
Architect + planning£6,000
Building control£1,200
HMO licence£1,000
Total cash required£412,500
② Bridge Structure
Purchase loan£350,000
Refurb budget£200,000
Contingency reserve£20,000
Total facility£570,000
Bridge interest ⓘ £45,600
Facility£570,000
Avg utilisation (80%)£456,000
Rate × duration10% × 12mo
Total interest£45,600
Total to repay£615,600
③ Gross Development Value
6 rooms × £950 × 12 = £68,400/yr gross − 5% void = £64,980 adjusted × 0.85 = £55,233 net/yr ÷ 6.0% yield = £920,550 GDV
Gross annual rent£68,400
Void-adjusted£64,980
Net income (×0.85)£55,233
GDV£920,550
Purchase £500kGDV £921k
④ Refinance & Capital Return
New BTL mortgage (75% LTV)£690,413
Bridge repaid ⓘ −£615,600
Principal£570,000
Interest£45,600
Total£615,600
Cash returned to you£74,813
Net capital still in deal£337,687
£75k returned£338k still in
⑤ Monthly Income Split
Gross rent (6 rooms)£5,700
BTL mortgage ⓘ −£3,165
Loan£690,413
Rate5.5% p.a.
Monthly (IO)£3,165
Net rent after mortgage£2,535
OES share (50%)−£1,268
Your monthly income£1,268
Mortgage56%
Your income22%
OES share22%
Annual income£15,216
Return on net capital4.5%
⑥ Exit at 5 Years
Property value£1,119,000
Outstanding mortgage£690,413
Equity£428,587
Cumulative income£76,080
Total return£504,667
Profit above capital invested
This deal FTSE Savings

⚠️ Illustrative projections only. Not financial advice. Capital at risk. SDLT rates as of 26 March 2026.

Real Example

Case Study: Victoria House, SE8

A complete OES JV deal — Victorian terrace in Deptford, acquired below market, converted to a 10-room HMO, refinanced 12 months later with full investor capital returned.
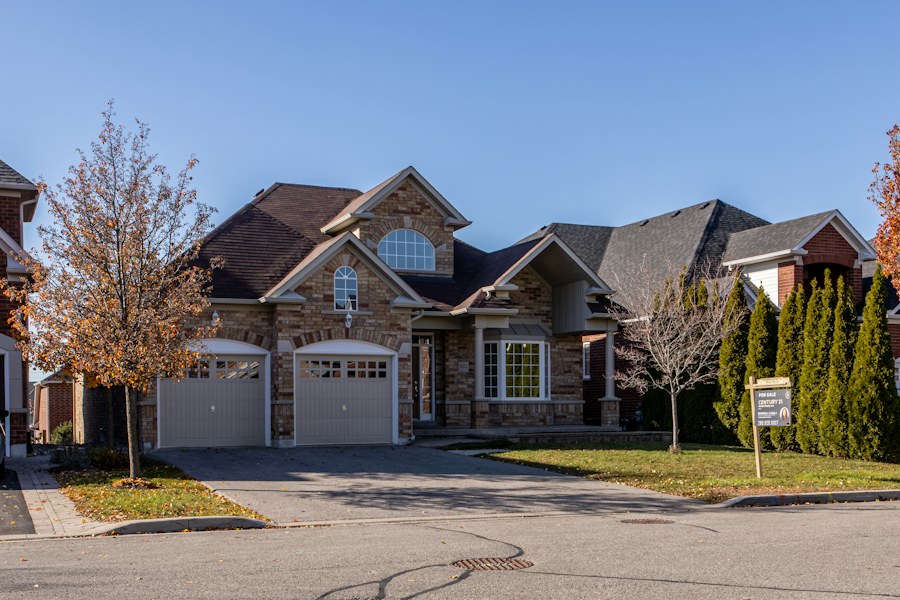
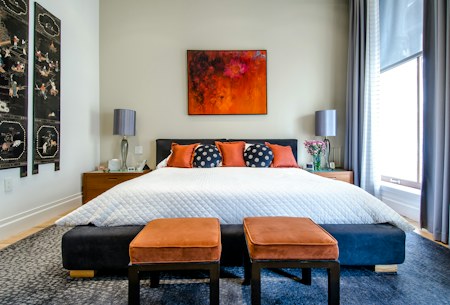
Victorian terrace Deptford SE London En-suite bedroom Designer kitchen
📥 Capital In
Purchase Price £600,000
30% Deposit £180,000
Fees + SDLT £45,000
Total Investor Cash £225,000
🏗️ Bridge Structure
Purchase Loan (70%) £420,000
Refurb Loan (100%) £250,000
Bridge Interest (12mo) £53,600
Total Facility £670,000
📈 GDV & Refinance
10 rooms × £800/mo £96,000/yr
GDV at 6% yield £1,360,000
Refinance (75% LTV) £1,020,000
Cash Released £296,400
💸 Capital Flow
↓
Investor puts in
Deposit + fees + SDLT
£225,000
🏦
Bridge repaid
£670k principal + £53.6k interest
£723,600
↑
Cash returned
£1,020k refi − £723.6k bridge
£296,400
✓
Net capital left in deal
£296,400 returned > £225,000 in
£0
+£71,400 SURPLUS
📊 Annual Income (Post-Refinance)
Gross rental income £81,600
Mortgage interest (5%) −£51,000
Net profit after mortgage £30,600
50 / 50 Split
Investor
£15,300
per year
OES
£15,300
per year
⚠️ Sensitivity Analysis

How deal viability changes as yield moves. Below 6%, investor capital is fully returned. Above 7%, capital may remain in deal.

Yield GDV Refinance (75%) Cash After Bridge Surplus / Gap Status
5% £1,632,000 £1,224,000 £500,400 +£275,400 Strong
6% ← Base Case £1,360,000 £1,020,000 £296,400 +£71,400 ✓ Full Return
7% £1,165,714 £874,285 £150,685 −£74,315 Partial
8% £1,020,000 £765,000 £41,400 −£183,600 At Risk
Investor capital left in
£0
Fully recycled + £71k surplus
Annual income (investor)
£15,300
On zero capital remaining = ∞ ROI
Asset value (GDV)
£1.36M
Owned outright in investor's name

⚠️ Figures are illustrative projections based on the stated assumptions. Actual returns depend on market conditions, final refurbishment costs, achieved rents, and RICS valuation at refinance. This is not financial advice.

End-to-End Process

What We Do — Every Step

From property search to managing your tenants years later — we handle every element.

01
🔍

Property Sourcing

Off-market Victorian properties in SE London, typically 15–25% below market value, with strong HMO potential.

02
📋

Initial Surveys

Pre-acquisition structural surveys, HMO feasibility, and planning consultation before any money is committed.

03
📐

Planning & Design

Architects, planning consultants, and structural engineers handle all applications and council liaison.

04
🏗️

Full Refurbishment

Complete HMO conversion: fire doors, alarms, EICR electrics, en-suites, designer fit-out — to full Building Regs.

05
📜

All Certificates

Gas Safety, EICR, Fire Commissioning, EPC, HMO Licence — all secured before any tenant moves in.

06
🏠

HMO Licensing

Full HMO licensing managed start to finish — property legally compliant and approved before launch.

07
🏦

Refinance

RICS valuation arranged, BTL mortgage drawn, bridging repaid — surplus returned to investor.

08
🔑

Lettings & Management

Full lettings, tenant management, compliance, maintenance, monthly statements — permanently. You receive income.

Common Questions

Frequently Asked Questions

For a typical SE London Victorian terrace at £400k–£500k, a 25% deposit means £100k–£125k. Add refurbishment (typically £180k–£220k) and total capital required is usually £280k–£350k. We can discuss phased or co-investment structures if needed.
Yes — purchased in your name or company (an SPV is often used for tax efficiency). OES holds no ownership stake. Our fee comes from the 50% net rent split. You own a genuine freehold asset, not a share in someone else's portfolio.
Typically 8–12 months: 4–8 weeks acquisition, 6–8 months refurbishment and licensing, 2–4 weeks to let, 1 month for refinance. You are not earning income during the bridge period — this is built into our projections.
Our average void period is 8 days. Our co-living rooms typically receive 40–60+ enquiries each. Demand currently far exceeds supply in SE London. If a void does occur, the mortgage still falls due — investors should hold reserves for this normal property risk.
In all our completed deals, the new mortgage has covered the bridge in full. However, if GDV uplift is lower than projected (market downturn, planning issues), a shortfall could arise. We mitigate this by conservative property selection and building buffers into our GDV projections.
OES earns 50% of net rent after mortgage — ongoing. We also charge a sourcing fee (typically 2% of purchase price) and a project management fee (typically 10% of refurb budget). All costs are documented in the JV agreement before any money changes hands. No hidden fees.
Yes — you own the property and can sell at any time. Early repayment charges may apply on the BTL mortgage within the first few years, and 3 months notice applies under our management agreement. Most investors hold 5+ years to maximise returns.
No. OES is a property management company, not a regulated financial adviser. Nothing on this page constitutes regulated financial advice. All projections are illustrative. Seek independent legal and financial advice from FCA-authorised professionals before investing. Your capital is at risk.
Take the Next Step

Ready to Discuss Your
Investment?

Our team will walk you through the full opportunity with live properties and real numbers. No obligation.

Book a Discovery Call → ⬇ Download Brochure Investor Portal

Capital at risk. Property values can fall as well as rise. This page does not constitute regulated financial advice. Please seek independent advice before investing.